“Never spend” sounds disciplined, but it is usually a short lived rule. People still need groceries, gas, school supplies, medicine, and the occasional surprise fix that shows up on a Tuesday. When spending is treated like failure, even normal life can feel like blowing the plan.
A better goal is to spend on purpose. That means giving your money jobs before it leaves your account, instead of judging every purchase after the fact. It is less dramatic than a no spend challenge, but it works better because it fits real life. If you are sorting through day to day cash pressure, debt, or options like bad credit title loans, that difference matters. The goal is not to become a person who never spends. The goal is to become a person who knows what each dollar is doing.
This shift sounds small, but it changes the whole mood of money management.
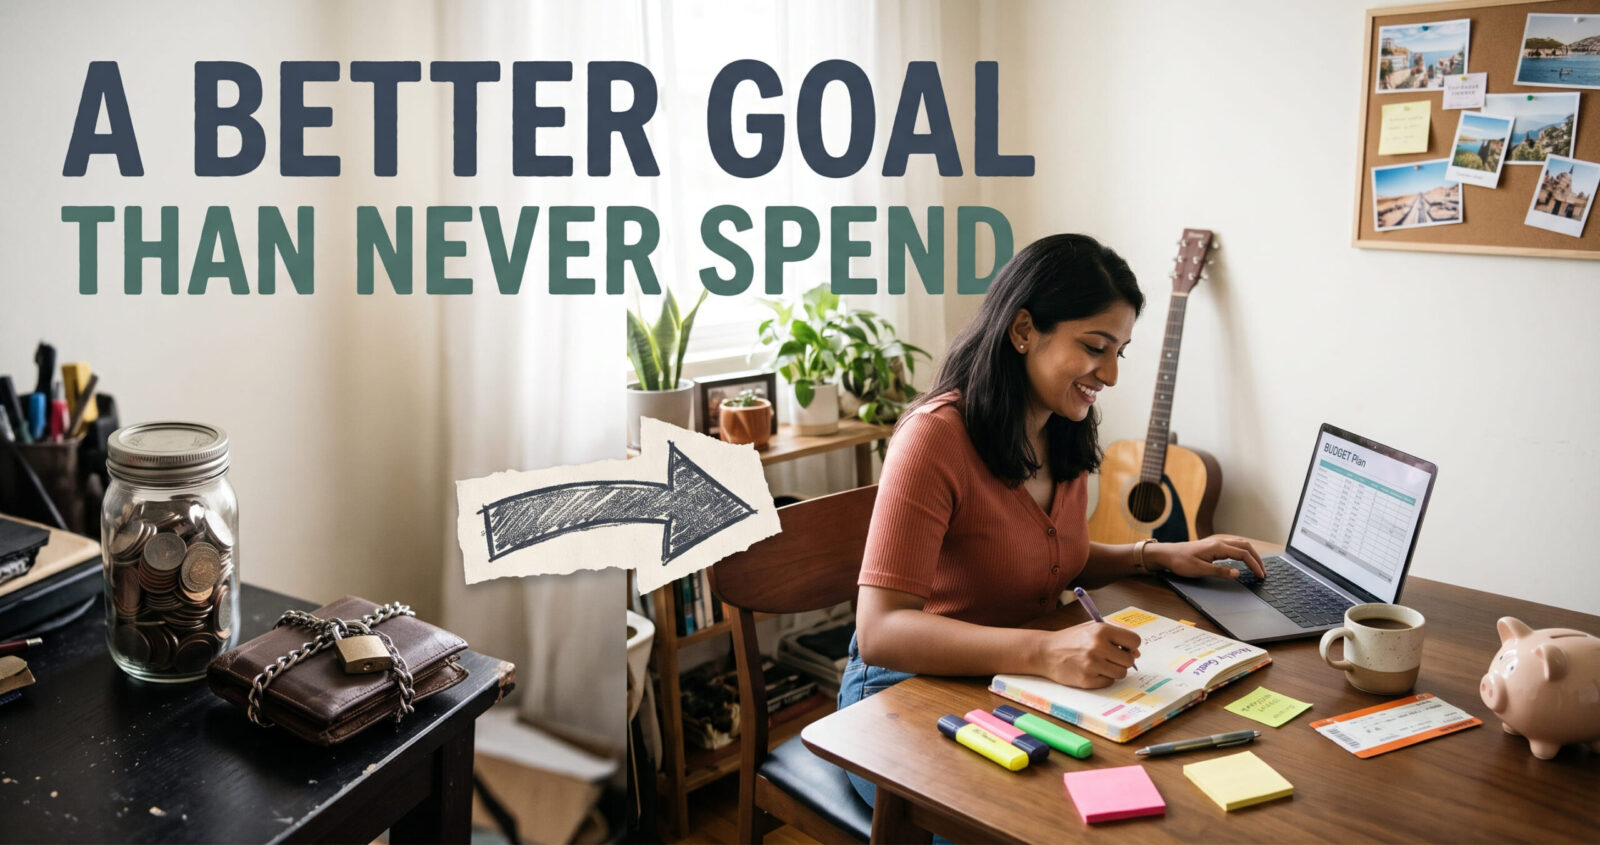
“Never spend” turns every expense into a temptation.
“Spend on purpose” turns expenses into choices.
You stop asking, “Can I be perfect this week?” and start asking, “What matters most before I get paid again?”
Why strict spending bans often backfire
A hard ban can be useful for a very short reset, especially if impulse buying has gotten out of hand. But as an everyday strategy, it can create all or nothing thinking. One takeout meal or one forgotten fee can make the whole effort feel ruined. After that, it is easy to slip into, “Well, I already messed up, so what difference does one more purchase make?”
That pattern lines up with Consumer Financial Protection Bureau research on managing spending. The agency found that many people want to budget, but often do not use a budget in the moment when an actual purchase decision appears. It also notes that tracking spending can feel overwhelming or like too much hassle. That helps explain why good intentions do not always turn into daily habits. People usually need a system that is practical enough to use under pressure, not a rule that depends on perfect willpower.
A rule that ignores reality can also hide important differences between spending types. Paying a late fee is not the same as buying concert tickets. Replacing worn work shoes is not the same as adding another random package to the porch. When every dollar is labeled bad, you lose the ability to make smart tradeoffs.
A more useful goal: lower regret spending
Instead of trying to spend less in every category, aim to reduce regret. That means looking for the purchases that consistently make life better and trimming the ones that leave you wondering where the money went.
Try sorting spending into three buckets:
- Essential and stabilizing, like housing, utilities, food, transportation, prescriptions, and minimum debt payments.
- Valuable and chosen, like a gym membership you actually use, a birthday dinner you planned for, or a streaming service the whole household enjoys.
- Leaky spending, like convenience buys, duplicate subscriptions, rush shipping, fees, and boredom purchases.
The third bucket is where many people find room. Not because they are careless, but because leaky spending tends to happen when tired, rushed, stressed, or distracted. A better system catches those moments before they stack up.
How to spend on purpose without tracking every penny
Start with a short list.
- First, cover the non-negotiables. Know the bills that must be paid before anything extra happens.
- Second, set one weekly limit for flexible spending. This is your money for food stops, small household extras, entertainment, and the little things that can blur together. A weekly number is often easier to manage than a monthly one.
- Third, create friction for your most common weak spot. Delete stored card info, unsubscribe from marketing texts, or wait 24 hours before buying nonessential items.
- Fourth, leave a small amount for joy. If your plan has no room for pleasure, it often becomes a rebellion waiting to happen.
A simple spending plan also works better when it matches the timing of your life. If your phone bill hits three days before payday, that timing matters as much as the amount. Looking at due dates, paycheck dates, and recurring charges can reveal why some months feel impossible even when income has not changed.
The hidden win is better decisions under stress
Purposeful spending does more than protect your checking account. It can also help you respond better when life gets expensive. If you already know your fixed costs, your weekly flex number, and your spending leaks, you have a clearer picture of what can bend and what cannot.
That clarity matters when you are comparing financial options or trying to recover from a rough month. It also helps when reviewing your credit profile, since your credit report can affect access to future borrowing and other financial choices. You can request free credit reports through the official site authorized by federal law. Checking where you stand can be part of spending on purpose, because informed decisions are usually cheaper than surprised ones.